When the Exchange Rate Becomes the Deal: How Southeast Asia's Monetary Policies Are Rewriting the Rules for US Investors
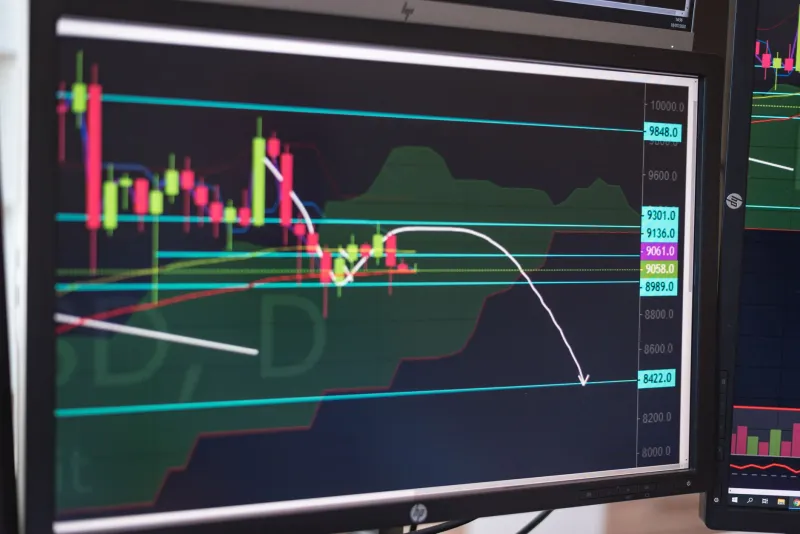
For most of the past decade, American companies entering Southeast Asia treated currency risk as a manageable line item — something to be addressed by the treasury department after the strategic decision had already been made. That approach is no longer adequate. Across the region, central bank interventions, diverging inflation trajectories, and capital flow restrictions are collectively reshaping the economics of cross-border investment in ways that are catching even experienced US firms off guard.
The Indonesian rupiah, the Vietnamese dong, the Thai baht, and the Philippine peso do not move in lockstep. Each is managed — or not managed — according to domestic political priorities, export competitiveness concerns, and foreign reserve calculations that often have little to do with what American investors might anticipate based on macroeconomic fundamentals alone. For US companies with meaningful exposure across multiple Southeast Asian markets, this divergence is creating a currency mosaic that demands a fundamentally different analytical framework.
The Illusion of Stability
On the surface, several Southeast Asian currencies appear relatively stable when measured against the US dollar over multi-year periods. That surface-level reading, however, obscures the volatility that occurs within individual quarters — volatility that can materially affect the dollar-denominated returns on acquisitions, joint ventures, and long-term supply contracts.
Vietnam's State Bank, for example, has historically maintained a tightly managed dong through a combination of direct intervention and capital controls. When the Federal Reserve began its aggressive rate-hiking cycle in 2022, the dong came under significant pressure as dollar-denominated assets became more attractive globally. The State Bank's response — drawing down foreign reserves to defend the currency — created a period of artificial stability that masked underlying stress. US investors who priced deals during that window and then settled them months later found that the apparent predictability had not fully insulated them from adverse movements.
Similar dynamics have played out in Indonesia, where Bank Indonesia has repeatedly intervened to support the rupiah during periods of global risk aversion. The interventions themselves are not the problem; the problem is that American firms accustomed to more transparent, market-driven currency mechanisms often fail to anticipate the timing and magnitude of policy shifts in managed-currency environments.
Where Opportunity Hides Inside Volatility
Not every currency story in Southeast Asia is one of risk management failure. A growing cohort of US firms — particularly those with dedicated regional treasury functions or external advisors with on-the-ground experience — are actively timing market entries around monetary policy cycles to extract meaningful financial advantages.
The Thai baht, for instance, has at various points traded at levels that made Thai manufacturing assets significantly cheaper for dollar-denominated buyers. Companies that tracked the Bank of Thailand's policy signals closely and moved acquisition timelines to coincide with baht weakness were able to enter at valuations that, when measured in US dollars, were substantially more attractive than headline price-to-earnings multiples suggested. This kind of currency-aware deal timing is not speculation — it is rigorous financial planning applied to a dimension of the transaction that less sophisticated buyers routinely ignore.
Malaysia presents a particularly instructive case. The ringgit has experienced pronounced weakness against the dollar in recent years, driven in part by domestic fiscal concerns and commodity price sensitivity. For US companies acquiring Malaysian assets or locking in long-term service contracts priced in ringgit, this has created a window in which dollar purchasing power stretches considerably further than it did five years ago. The question is whether those companies have the analytical infrastructure to recognize and act on such windows before conditions change.
Why Traditional Hedging Instruments Are Coming Up Short
The conventional toolkit for managing currency exposure — forward contracts, options, natural hedges through local-currency revenue matching — remains relevant in Southeast Asia, but it is increasingly insufficient on its own. Several structural features of the region's currency markets create limitations that US treasury teams trained primarily on G10 currencies may not fully appreciate.
Liquidity in forward markets for currencies such as the dong and the Myanmar kyat is limited, and bid-ask spreads can be wide enough to erode the economic benefit of hedging in the first place. Some currencies face outright restrictions on offshore hedging instruments, meaning that US firms must manage exposure through onshore mechanisms subject to local regulatory approval — a process that can be slow and unpredictable.
Beyond liquidity constraints, the correlation assumptions embedded in many standard hedging models break down in Southeast Asia. During periods of regional stress, currencies that typically move independently can become highly correlated, undermining the diversification benefits that US multinationals with multi-country exposure might otherwise expect. The 2013 taper tantrum and the 2020 pandemic shock both illustrated how quickly regional currency correlations can spike, leaving hedging positions that looked prudent in isolation suddenly inadequate in aggregate.
Building a More Sophisticated Regional Framework
US investors and corporate treasurers who are succeeding in this environment share a common characteristic: they treat Southeast Asian currency management as a specialized discipline rather than an extension of their existing global forex operations.
Practically, this means maintaining relationships with local financial institutions that have genuine insight into central bank policy intentions — not just the public statements, but the informal signals that experienced regional bankers learn to read. It means structuring deal terms with currency contingencies that would be unusual in a North American or European context, such as price adjustment mechanisms tied to exchange rate bands. And it means building regional treasury capacity that is physically present in the markets being managed, rather than relying exclusively on oversight from New York or Chicago.
Several US private equity firms active in the region have begun embedding currency scenario analysis directly into their investment committee materials, treating adverse exchange rate movements as a base-case risk rather than a tail risk. This shift in internal framing has, in some cases, led to deal structures that would have seemed overcautious a decade ago — earnout provisions denominated in dollars, escrow arrangements held in Singapore-domiciled accounts, and revenue-sharing agreements with local partners designed to create natural hedges at the operating level.
The Monetary Policy Variable That Boards Are Still Underweighting
Despite growing awareness of currency complexity in Southeast Asia, many US corporate boards continue to receive investment proposals in which exchange rate risk is treated as a sensitivity analysis footnote rather than a central variable. This is a governance gap that is becoming harder to justify as the region's monetary landscape grows more consequential.
Central banks across ASEAN are navigating their own versions of the same dilemma that confronted the Federal Reserve: how to balance inflation control, growth support, and currency stability in an environment shaped by external pressures they cannot fully control. Their decisions will continue to create both headwinds and tailwinds for American capital operating in the region.
For US investors, the imperative is clear. Currency analysis must move from the appendix to the executive summary. The firms that make that transition earliest will not merely avoid losses — they will identify opportunities that their less attentive competitors will miss entirely.